Control benefit costs.
Keep your people
covered and cared for.
Healthcare inflation is running north of 10%. We build employee benefits programs that hold the line on spend — self-funded and level-funded plans, HSAs and HRAs, compliance done right — without cutting what your team actually values.
One team for benefits, compliance, and everything in between.
Most employers juggle a broker, a compliance vendor, and an HR platform that don't talk to each other. We handle all three — so strategy, paperwork, and administration stay in sync.
Health Insurance & Employee Benefits
Plan design and funding strategy built around your actual claims, census, and budget — not a template.
- Self Insured / Self Funded
- HRAs, HSAs, and FSAs
- Benefits & HR Administration Platforms
- Absence Management & State Leave Exemption
- International Medical Coverage
- State & Federal SHOP Small Business Market
- Medicare and Retiree Plans
- Dental & Vision · Disability Income · Wellness · Commuter
Compliance & HR
The filings, notices, and documents that quietly create liability — tracked, prepared, and filed on schedule.
- ACA Information Reporting: IRC §6055 & §6056
- Employer Shared Responsibility: IRC §4980H
- ERISA Plan Documents
- Section 125 Plans
- COBRA Administration
- FMLA and Absence Management
- HR Information Systems & cloud dashboard
- Payroll integration
Non-group & Voluntary Coverage
For owners, retirees, contractors, and employees who need coverage outside the group plan.
- Individual and Family Health Insurance
- Life Insurance
- Medicare Supplement, Advantage & Part D
- Disability Income
- Self Employed Health Insurance
- Global & Travel Medical
- Dental · Accident · Critical Illness
Proactive, not once a year.
A renewal letter should never be the first conversation you have about your benefits. We work the plan year-round — reviewing claims, testing funding alternatives, and getting ahead of the compliance calendar before deadlines turn into penalties.
Understand the actual spend
We start with your census, claims experience, contribution strategy, and current carrier position — the real numbers, not a brochure comparison. That's what tells us where the leverage is.
Model the alternatives side by side
Fully insured, level-funded, or self-funded. HSA or HRA pairing. Narrow network options. Private exchange. You see the cost, risk, and employee impact of each before you decide anything.
Implement without disruption
Enrollment, carrier onboarding, HRIS and payroll integration, employee communication. Your team shouldn't feel a change in funding structure — that's the point.
Stay ahead of compliance and cost
ERISA documents, §125, ACA reporting, COBRA, state leave exemptions, and absence management — tracked on a calendar we own. Plus quarterly check-ins so next year's renewal isn't a surprise.
What a specialist broker does differently.
Most agencies quote your renewal and disappear until next fall. Here's where that model breaks down — and what we do instead.
Waugh Agency, LLC delivers customizable benefits that drive higher employee loyalty, and provide genuine, data-driven attention for long-term resilience.
What's changing this month.
Regulatory shifts, carrier moves, and cost drivers — explained for the people who have to act on them.
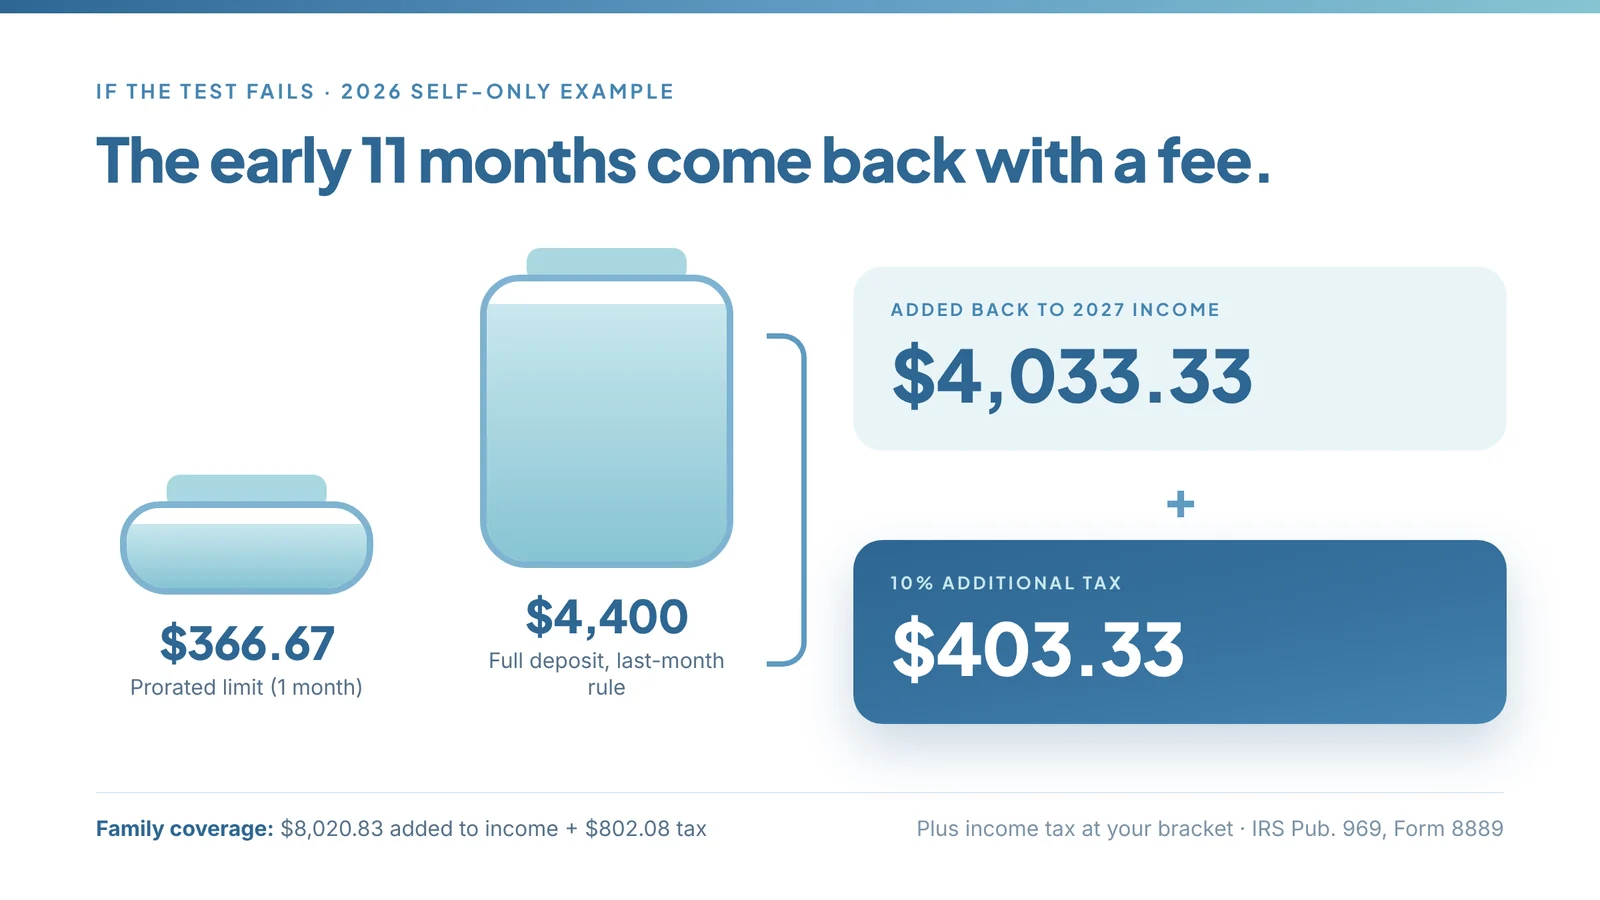 HSA Last-Month Rule: One Month of Coverage, a Full Year’s ContributionIf your HDHP starts by December 1, you can deposit the full annual HSA limit.Read article →HSA Last-Month Rule: One Month of Coverage, a Full Year’s ContributionIf your HDHP starts by December 1, you can deposit the full annual HSA limit.Read article →
- Level Funded ACA Escape ValveThe small-group market split in two, and this guide helps you pick your 2027 path.Read article →Level Funded ACA Escape ValveThe small-group market split in two, and this guide helps you pick your 2027 path.Read article →
 July 2026 Healthcare Bills: Small Group Plan ImpactOn July 22, 2026, a Senate committee advanced bills that can change plans for groups of 25–125 employees.Read article →July 2026 Healthcare Bills: Small Group Plan ImpactOn July 22, 2026, a Senate committee advanced bills that can change plans for groups of 25–125 employees.Read article →
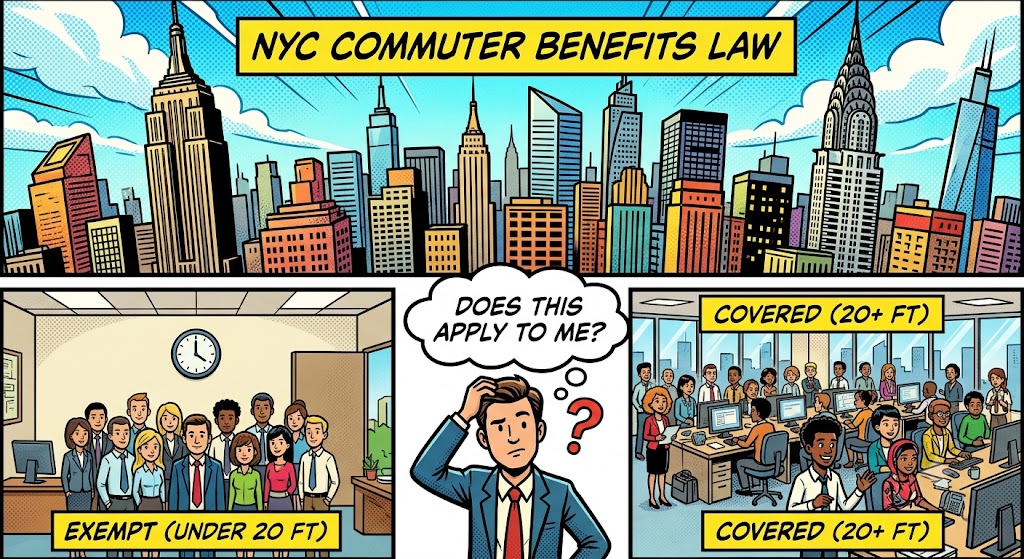 NYC Commuter Benefits Law: 2026 Employer GuideNew York City firms with 20 or more employees must offer a pre-tax transit benefit.Read article →NYC Commuter Benefits Law: 2026 Employer GuideNew York City firms with 20 or more employees must offer a pre-tax transit benefit.Read article →
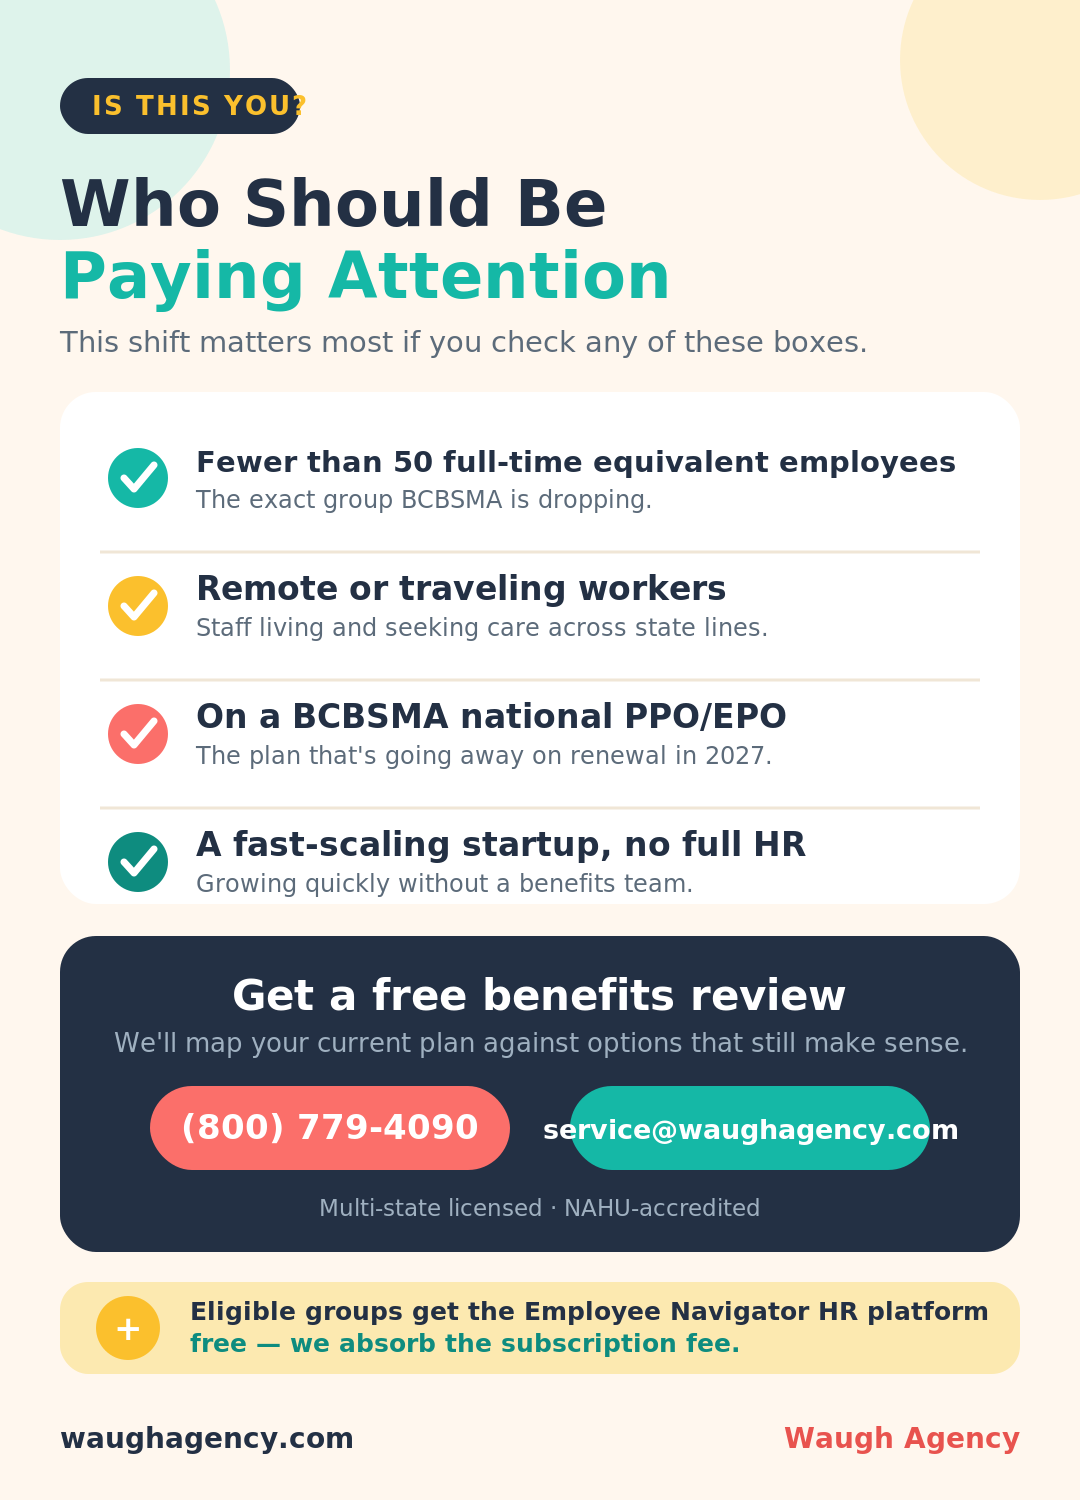 BCBSMA Drops Small-Group PPOs: A Self Funded Plan May HelpA self-funded plan can cover a multi-state team after the small-group national PPO and EPO plans end.Read article →BCBSMA Drops Small-Group PPOs: A Self Funded Plan May HelpA self-funded plan can cover a multi-state team after the small-group national PPO and EPO plans end.Read article →
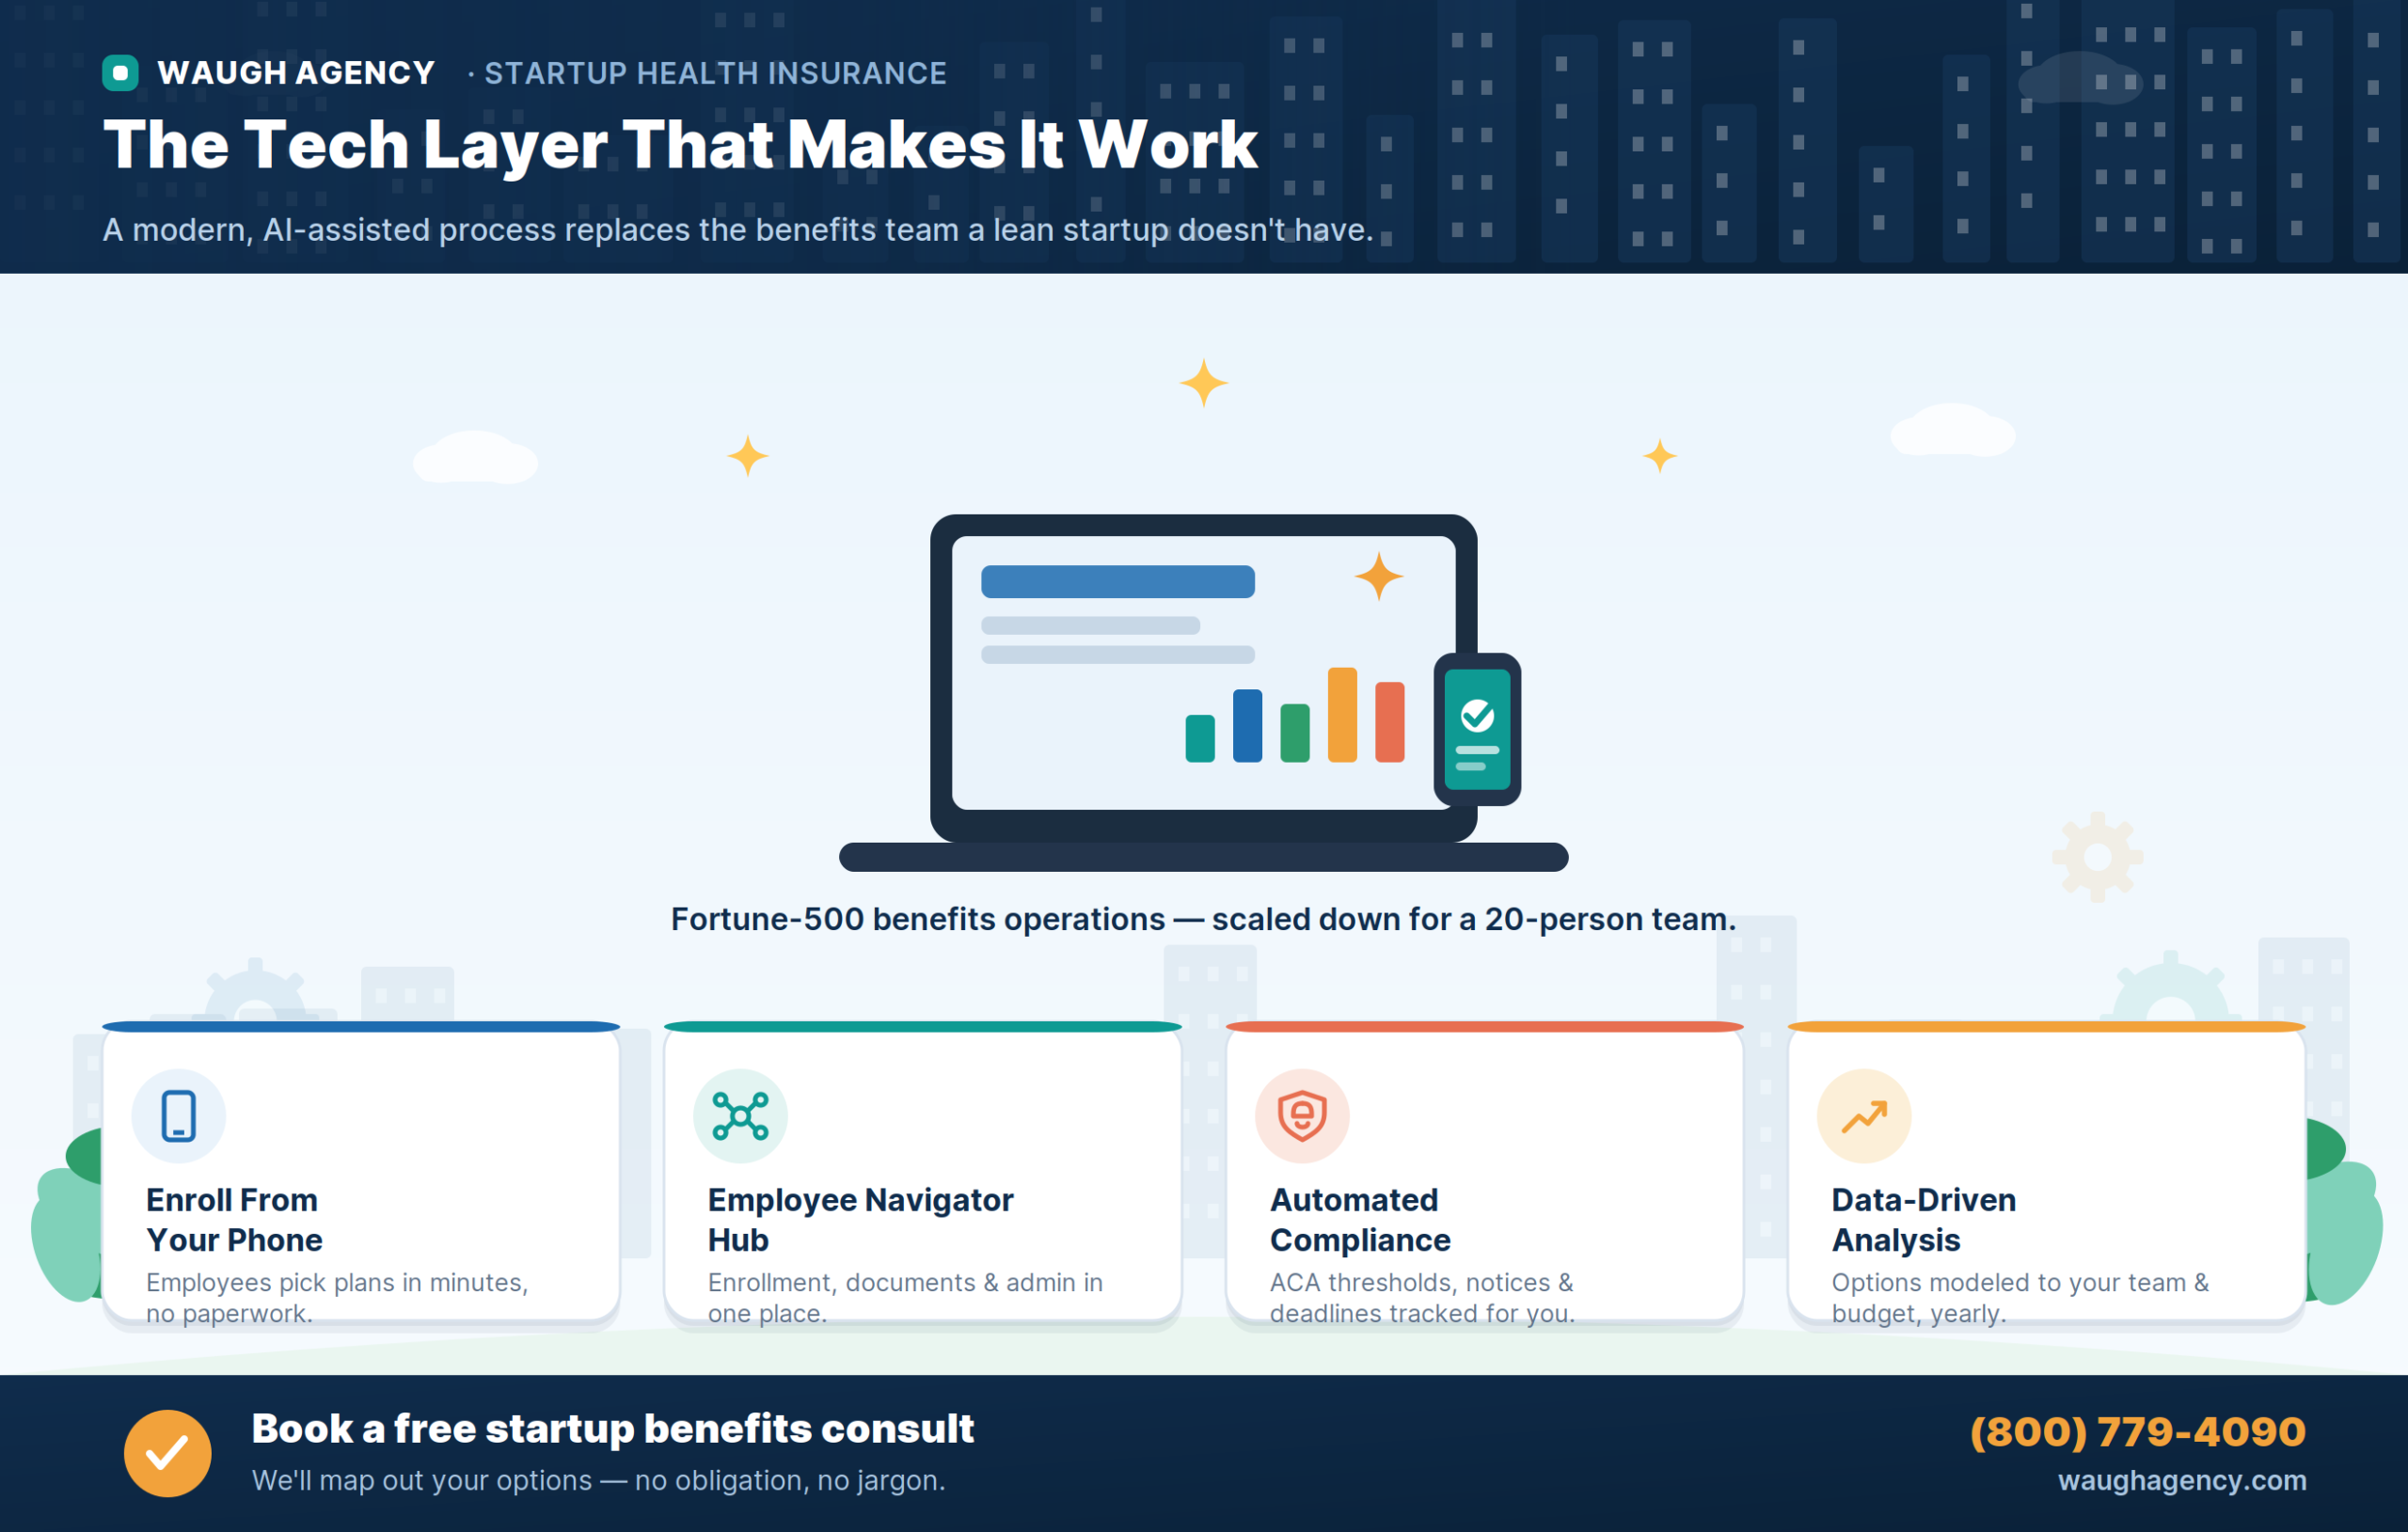 Startup Health Insurance: Build Your First Health PlanBuild a first group health plan that attracts talent and stays compliant as your company grows.Read article →Startup Health Insurance: Build Your First Health PlanBuild a first group health plan that attracts talent and stays compliant as your company grows.Read article →
Let's customize your 2026 benefits strategy.
Tell us a little about your group and we'll come back with a real read on where your costs are going — and what you can do about it.